AI is no longer only a software investment category. Its next phase depends on the physical systems, power contracts and long-duration capital that make intelligence available at scale.
On September 3–4, 2026, Valarty convened a private group of investors, founders, infrastructure specialists and strategic operators at Wilmina Berlin, in Berlin, Germany, for a two-day discussion on the capital architecture behind the expansion of artificial intelligence.
Attendance was restricted to approximately 50 invited participants. The setting was deliberately selective and discussion-oriented: a room designed for substantive exchange rather than conference-scale presentation. Berlin supplied more than a backdrop. As a European technology hub and a meeting point for founders and international capital, the city offered an appropriate place to examine who will finance the physical infrastructure required for AI to scale.
The economics of artificial intelligence are migrating down the stack. Models and applications remain important, but access to GPUs, power, cooling, land, networks and patient capital increasingly determines which companies can build, serve customers and defend margins.
AI Is Becoming an Infrastructure Industry
For much of the venture cycle, AI was described primarily through software: model performance, developer tools, vertical applications and new user experiences. That view is now incomplete. Training and inference require a coordinated physical system extending from advanced semiconductors and high-bandwidth memory to racks, optical networks, substations, cooling systems and long-term electricity supply. Cloud interfaces may make compute feel intangible, but the underlying capacity is engineered, financed and located.
Compute therefore behaves increasingly like a strategic resource. Availability can affect product roadmaps; reservation terms can affect cash requirements; cloud dependency can shape gross margin; and dedicated clusters can become either an advantage or a stranded commitment. For an AI-native company, infrastructure choices are no longer confined to the technical organisation. They belong in company strategy, treasury planning and board-level risk analysis.
“AI's next frontier will be financed twice: first as technology, then as infrastructure. Durable advantage will belong to companies that align compute, power and patient capital before demand forces the issue.” — Sancler Requião Barreto, Founder & CEO of Valarty
The Capital Behind Compute
The Berlin discussion returned repeatedly to a mismatch of duration. Venture capital is designed to finance uncertain product and market creation. A data center, by contrast, combines long-lived physical assets, construction risk, contracted power, equipment cycles and utilisation assumptions. GPU infrastructure sits between those worlds: technologically dynamic, capital-intensive and exposed to both asset obsolescence and demand volatility.
That is why no single financing instrument can carry the entire stack efficiently. Venture equity may be appropriate for software orchestration, differentiated cloud services or an AI platform proving demand. Infrastructure funds and private equity can underwrite mature facilities and contracted cash flows. Project finance becomes relevant when assets, permits, counterparties and revenue commitments are sufficiently defined. Credit can fund equipment or working capital when repayment is linked to observable utilisation. Strategic partners and corporate balance sheets may anchor capacity where access itself is central to competition.
The institutional question is not simply how much capital is available. It is whether each risk is matched to the capital capable of carrying it. Using expensive equity to finance predictable infrastructure can dilute the technology layer; applying asset-based debt before demand is bankable can create fragility. Capital architecture is therefore part of product architecture.
Why Data Centers Have Entered the AI Investment Thesis
AI workloads change the operating assumptions of the traditional data-center model. Higher power density alters rack design, electrical distribution and cooling requirements. Accelerator clusters need high-speed interconnection and can create concentrated thermal loads. Land remains important, but its value is inseparable from grid access, fibre connectivity, permitting, water or alternative cooling capacity and the ability to expand.
Utilisation is equally consequential. A facility can be technically impressive while producing weak returns if committed capacity arrives before customers, if workloads migrate, or if hardware depreciates faster than the financing schedule. Training capacity and inference capacity also have different profiles. Training may be episodic and concentrated; inference can become geographically distributed, latency-sensitive and embedded in customer operations. Investors must therefore ask not only what a site can host, but which workload it is built to serve and how demand will be contracted.
The International Energy Agency has projected that global electricity generation serving data centers could rise from roughly 460 TWh in 2024 to more than 1,000 TWh by 2030. That projection is not merely an energy statistic. It indicates the scale of generation, grid, construction and financing decisions that sit beneath the software market.
Energy Is Becoming a Technology Constraint
Electricity availability may be the most decisive constraint because it cannot be provisioned through software speed. Grid connections, substations and transmission upgrades operate on physical and regulatory timelines. The IEA estimates that grid constraints could delay around 20 per cent of the global data-center capacity planned for construction by 2030. In several European hubs, connection queues already extend for years.
This changes site selection and investment diligence. A credible project requires more than a power-purchase announcement. Investors need to understand firmness of supply, connection timing, curtailment exposure, local grid conditions, price risk and the relationship between contracted renewable generation and the electricity physically available at the site. Storage and demand flexibility can improve resilience, but they do not eliminate the need for dependable capacity.
Nuclear power and advanced geothermal systems have entered the discussion because they promise firm, low-carbon supply, while renewables remain central to incremental generation. The appropriate mix will differ by market and project. The investment principle is more stable: energy strategy must be integrated early, not treated as a procurement detail after the compute plan has been approved.
European Sovereignty and the Compute Question
Europe's opportunity is not to reproduce every element of the American hyperscale model. It is to build credible regional capacity around areas where sovereignty, industrial depth, energy efficiency and regulatory trust matter. Sovereign compute can give researchers, governments and companies greater control over data location, security and access. Specialist data centers can serve regulated or technically demanding workloads. Vertically integrated infrastructure providers can connect GPU capacity, cloud tooling and enterprise deployment without pretending that physical ownership alone creates defensibility.
The European policy direction increasingly recognises this connection. EuroHPC is expanding AI Factories and has opened a call for large-scale AI Gigafactories combining advanced processors, cloud stacks, connectivity and energy-efficient data centers. Public procurement can act as an anchor, while private capital carries construction and operating exposure. The European Investment Bank's 2026 summary for a proposed GPU infrastructure project in France and Sweden likewise describes the market failure directly: high upfront cost, uncertainty about future demand and uncertainty about the economic life of the assets.
These initiatives are important, but sovereignty should not become a substitute for economics. European facilities still need competitive utilisation, disciplined procurement, technical talent, reliable energy and customers willing to commit. Strategic autonomy is durable only when the infrastructure is also commercially credible.
What the Berlin Room Brought Into Focus
Sancler Requião Barreto, Founder & CEO of Valarty, centred his contribution on the transition from software-centric AI investing toward infrastructure-aware investment strategies. The discussion connected venture capital and emerging technology platforms with the institutions capable of financing long-duration assets. It also examined European competitiveness without assuming that public ambition alone resolves execution risk.
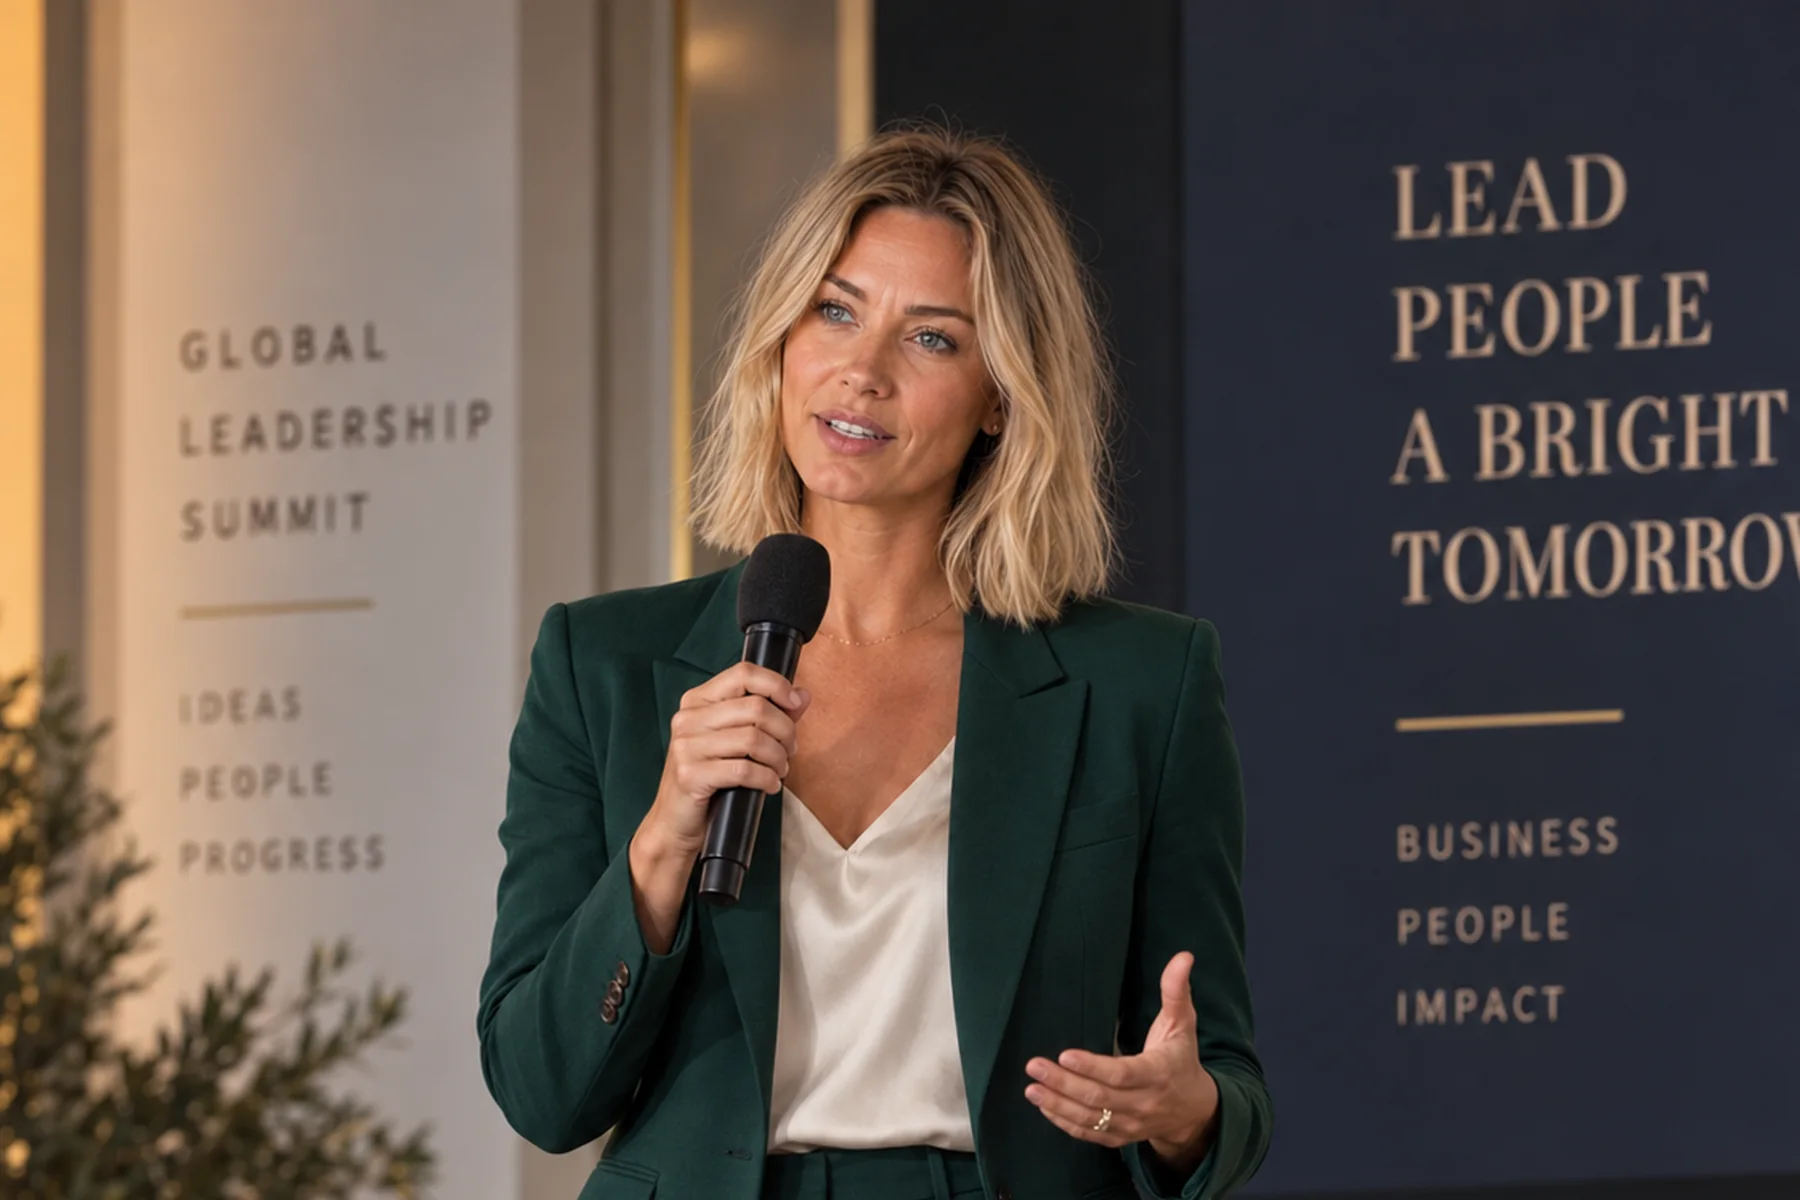
Anna Bangert participated in the Berlin discussions on behalf of Valarty. Her role in coordinating conversations helped connect the European technology ecosystem with investor-founder dialogue, cross-border perspectives and strategic relationships across the Valarty network. In a private format, this connective work matters: it allows technical, financial and operating perspectives to meet without reducing the session to a sequence of public pitches.
The participants represented the functions that must ultimately coordinate if infrastructure is to be built: investors weighing duration and risk, founders deciding how much of the stack to own, specialists assessing data-center and energy constraints, and strategic operators responsible for deployment. No investment transactions, commitments or partnerships were announced. The value of the room was analytical — a clearer map of the dependencies behind the next AI cycle.
Five Investment Conclusions From Berlin
Compute access is becoming part of company strategy. AI-native companies need a view on capacity, providers, portability and margin before scale turns infrastructure dependency into a negotiating weakness.
Energy has entered the AI investment thesis. Power availability, connection timing and cooling efficiency influence time to market, capital expenditure and the geography of competitive capacity.
Infrastructure finance will increasingly complement venture capital. Equity remains essential for technological uncertainty, but equipment, facilities and contracted capacity may require debt, project finance, infrastructure funds or strategic balance sheets.
Europe needs deeper pools of patient, technically informed capital. Sovereign ambition can anchor demand, yet private investors must still price construction, utilisation, hardware renewal and energy exposure with discipline.
Data-center economics are becoming inseparable from AI economics. Model capability does not remove the cost of serving workloads. The winners will understand the unit economics of compute as closely as they understand software adoption.
The Valarty View
Valarty's view after Berlin is that the AI stack should be underwritten as a connected capital system. At the top sit products, models and customer workflows. Beneath them sit cloud contracts, GPU clusters, networking, facilities and energy. Each layer carries a different duration, failure mode and financing logic. Investors who collapse those layers into a single “AI” category risk paying software valuations for infrastructure exposure or applying infrastructure conservatism to genuinely compounding technology.
For founders, the implication is equally practical. Owning more infrastructure is not automatically strategic; renting everything is not automatically capital-efficient. The correct boundary depends on workload, differentiation, customer requirements, security, latency and scale. A company should own the layer that strengthens its advantage and structure the remaining dependencies so they do not control its future.
What Comes Next
The next infrastructure cycle will be decided through portfolios of coordinated commitments: compute offtake, grid access, land and permits, equipment procurement, cloud distribution, customer contracts and long-duration capital. The pace of AI development makes these commitments difficult because physical assets must be planned before demand is fully visible. That tension cannot be eliminated; it can only be governed through staged capacity, credible anchor customers and transparent assumptions.
Wilmina Berlin gave Valarty an appropriately quiet setting in which to examine that tension. The two-day session did not produce a single formula for financing AI infrastructure. It produced something more useful: a shared recognition that compute, energy and capital allocation now belong inside the same investment memorandum. As AI moves further into the physical economy, that integrated view will become a condition of serious underwriting.
Research Notes
This post-event analysis distinguishes confirmed event information supplied by Valarty from independent editorial interpretation. It does not disclose private discussions, attribute statements to unnamed participants or imply investment commitments.
- International Energy Agency — Energy and AI
- International Energy Agency — AI and Energy Security
- European Commission — Energy Performance of Data Centres
- EuroHPC Joint Undertaking — AI Gigafactories Call
- European Investment Bank — European GPU Infrastructure Project Summary
- Hero image: Anna Bangert during Valarty's September 2026 Berlin discussions. Photo supplied by Valarty and stored locally; cropped and optimized for publication.
Disclaimer: Content published by VALARTY is for strategic, informational and institutional purposes only. It does not constitute investment advice, an offer to sell securities or a solicitation to invest. Forward-looking observations involve uncertainty and should not be treated as forecasts or commitments.